
تاریخ اشاعت: August 29, 2026 - 9:53 AM
New Law Excludes Agricultural Land from Real Estate REIT Investment Schemes
نئے قانون کے تحت زرعی زمین کو رئیل اسٹیٹ REIT انویسٹمنٹ سکیمز سے خارج کر دیا گیا
▫️ایس ای سی پی نے کیپٹل گین، کرایہ داری آمدن اور اربن رئیل اسٹیٹ پر مبنی REIT فریم ورک میں ترامیم تجویز کر دیں
Islamabad | ReNews PakistanThe Securities and Exchange Commission of Pakistan (SECP) has proposed amendments to the regulatory framework governing Real Estate Investment Trust (REIT) schemes, including a specific exclusion of agricultura...
Islamabad | ReNews Pakistan
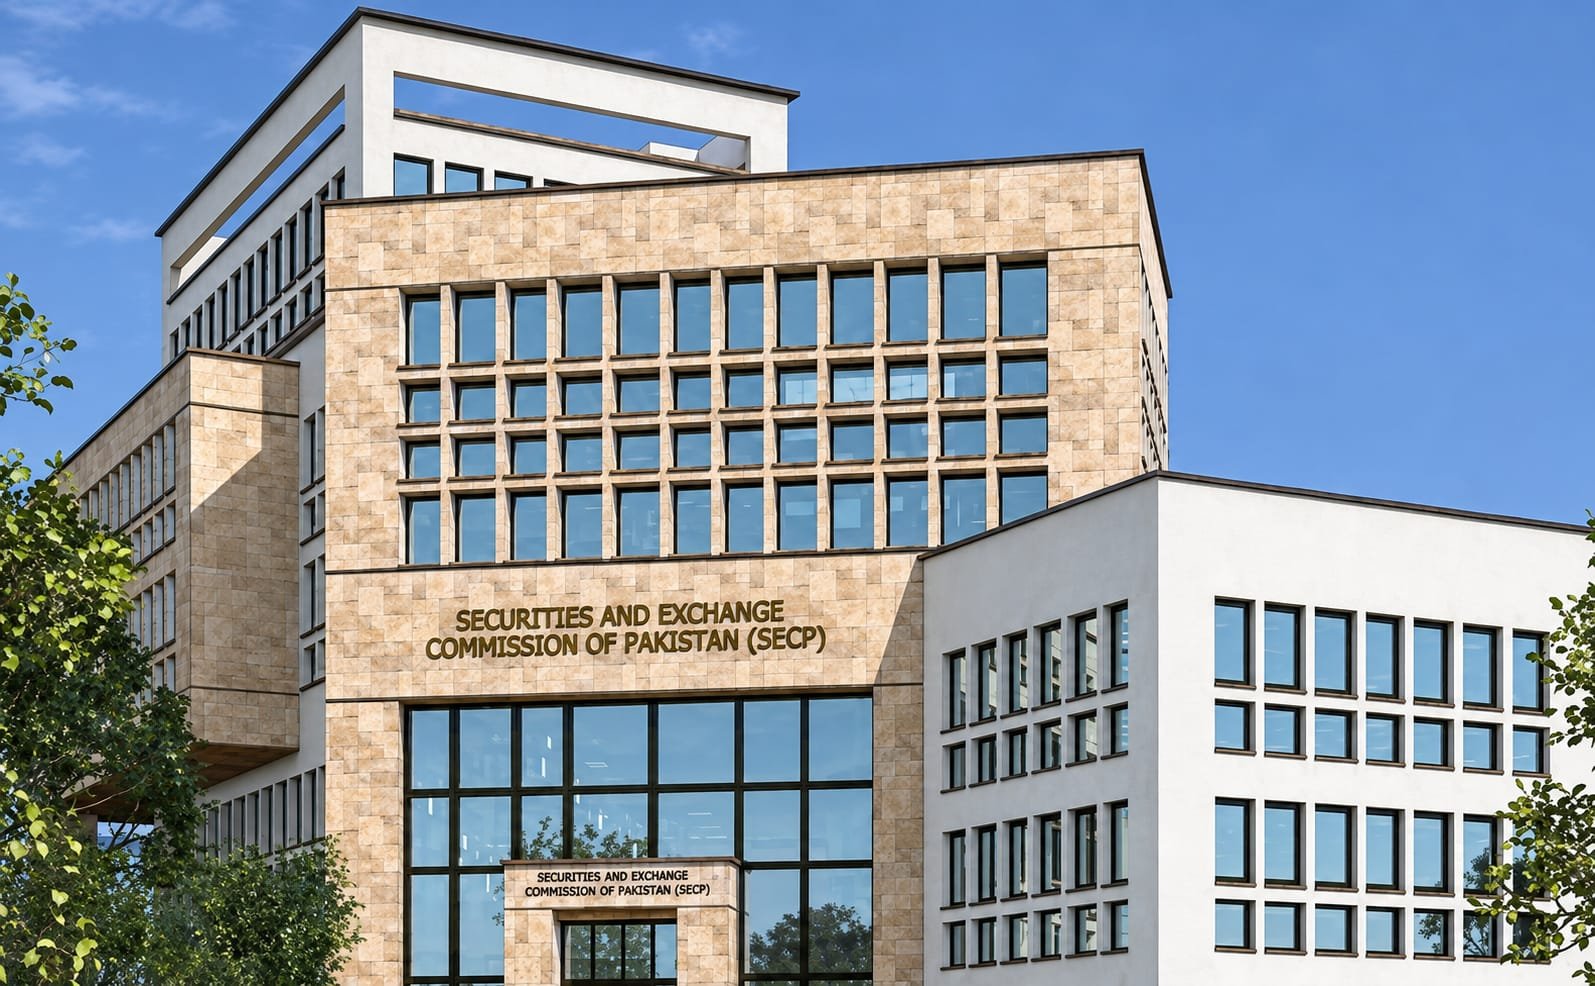
The Securities and Exchange Commission of Pakistan (SECP) has proposed amendments to the regulatory framework governing Real Estate Investment Trust (REIT) schemes, including a specific exclusion of agricultural land from investment-based REIT structures.
The proposed changes have been introduced through S.R.O. 1440(I)/2026, issued by the SECP on Friday, as part of draft amendments to the Real Estate Investment Trust Regulations, 2022.
Under the proposed framework, an investment-based REIT scheme would primarily be established to acquire real estate with the objective of generating capital gains. However, agricultural land would not qualify for inclusion in such investment-based REIT schemes, narrowing the category of assets that can be acquired through this investment structure.
The SECP has also specified that eligible real estate for investment based REIT schemes must be located within metropolitan cities. Where required under applicable laws and regulations, the property must also have the relevant No Objection Certificate (NOC), approval or permission from the competent authority.
The proposed amendments are aimed at providing greater clarity regarding the nature and location of properties that can form part of REIT investment portfolios while strengthening regulatory oversight of real estate-based investment vehicles.
The draft framework also introduces greater flexibility through the proposed recognition of hybrid REIT schemes. Such schemes would be able to combine investment-based and rental strategies, allowing them to generate rental income from properties while continuing to hold those assets for potential capital appreciation.
This structure could provide REIT managers with greater flexibility in managing property portfolios by allowing them to pursue both recurring rental returns and longer-term gains in property values.
The SECP has further proposed changes concerning the listing timeline of REIT schemes. Under the draft amendments, the regulator may grant an extension of up to one year for the listing of a rental or investment-based REIT scheme if the applicant provides valid reasons for the delay.
The proposed provision could offer additional flexibility to REIT sponsors facing circumstances that prevent them from completing the listing process within the prescribed timeframe, subject to the SECP's assessment of the reasons presented.
Another important change relates to real estate acquired from government entities, government-backed bodies or statutory development authorities. In such cases, the SECP may accept an irrevocable and legally binding transfer agreement as sufficient compliance with the property-transfer requirement, subject to conditions imposed by the regulator.
The measure could simplify the process of incorporating government-owned or authority-controlled properties into REIT structures by providing an alternative mechanism for demonstrating the legal basis of the property transfer.
The proposed amendments are part of the SECP's broader efforts to refine Pakistan's REIT regulatory framework and facilitate structured investment in the real estate sector while maintaining safeguards for investors and ensuring that qualifying properties meet applicable legal and regulatory requirements.
As the amendments have been issued in draft form, the proposed provisions remain subject to the regulatory process before becoming part of the applicable REIT framework.
The Securities and Exchange Commission of Pakistan (SECP) has proposed amendments to the regulatory framework governing Real Estate Investment Trust (REIT) schemes, including a specific exclusion of agricultural land from investment-based REIT structures.
The proposed changes have been introduced through S.R.O. 1440(I)/2026, issued by the SECP on Friday, as part of draft amendments to the Real Estate Investment Trust Regulations, 2022.
Under the proposed framework, an investment-based REIT scheme would primarily be established to acquire real estate with the objective of generating capital gains. However, agricultural land would not qualify for inclusion in such investment-based REIT schemes, narrowing the category of assets that can be acquired through this investment structure.
The SECP has also specified that eligible real estate for investment based REIT schemes must be located within metropolitan cities. Where required under applicable laws and regulations, the property must also have the relevant No Objection Certificate (NOC), approval or permission from the competent authority.
The proposed amendments are aimed at providing greater clarity regarding the nature and location of properties that can form part of REIT investment portfolios while strengthening regulatory oversight of real estate-based investment vehicles.
The draft framework also introduces greater flexibility through the proposed recognition of hybrid REIT schemes. Such schemes would be able to combine investment-based and rental strategies, allowing them to generate rental income from properties while continuing to hold those assets for potential capital appreciation.
This structure could provide REIT managers with greater flexibility in managing property portfolios by allowing them to pursue both recurring rental returns and longer-term gains in property values.
The SECP has further proposed changes concerning the listing timeline of REIT schemes. Under the draft amendments, the regulator may grant an extension of up to one year for the listing of a rental or investment-based REIT scheme if the applicant provides valid reasons for the delay.
The proposed provision could offer additional flexibility to REIT sponsors facing circumstances that prevent them from completing the listing process within the prescribed timeframe, subject to the SECP's assessment of the reasons presented.
Another important change relates to real estate acquired from government entities, government-backed bodies or statutory development authorities. In such cases, the SECP may accept an irrevocable and legally binding transfer agreement as sufficient compliance with the property-transfer requirement, subject to conditions imposed by the regulator.
The measure could simplify the process of incorporating government-owned or authority-controlled properties into REIT structures by providing an alternative mechanism for demonstrating the legal basis of the property transfer.
The proposed amendments are part of the SECP's broader efforts to refine Pakistan's REIT regulatory framework and facilitate structured investment in the real estate sector while maintaining safeguards for investors and ensuring that qualifying properties meet applicable legal and regulatory requirements.
As the amendments have been issued in draft form, the proposed provisions remain subject to the regulatory process before becoming part of the applicable REIT framework.
اسلام آباد | ری نیوز پاکستان
سکیورٹیز اینڈ ایکسچینج کمیشن آف پاکستان (SECP) نے رئیل اسٹیٹ انویسٹمنٹ ٹرسٹ (REIT) سکیموں کے ریگولیٹری فریم ورک میں ترامیم تجویز کر دی ہیں، جن کے تحت انویسٹمنٹ بیسڈ REIT سکیموں میں زرعی زمین کو شامل نہیں کیا جا سکے گا۔
ایس ای سی پی کی جانب سے یہ مجوزہ ترامیم S.R.O. 1440(I)/2026 کے ذریعے جمعہ کو جاری کی گئیں، جو رئیل اسٹیٹ انویسٹمنٹ ٹرسٹ ریگولیشنز 2022 میں مجوزہ ترامیم کا حصہ ہیں۔
مجوزہ فریم ورک کے تحت انویسٹمنٹ بیسڈ REIT سکیم کا بنیادی مقصد ایسی رئیل اسٹیٹ حاصل کرنا ہوگا جس سے مستقبل میں کیپٹل گین حاصل کیا جا سکے۔ تاہم، زرعی زمین کو اس نوعیت کی REIT سکیموں کے لیے اہل اثاثہ تصور نہیں کیا جائے گا، جس سے انویسٹمنٹ بیسڈ REIT پورٹ فولیو میں شامل کیے جانے والے اثاثوں کا دائرہ محدود ہو جائے گا۔
ایس ای سی پی کے مطابق انویسٹمنٹ بیسڈ REIT سکیموں کے لیے اہل رئیل اسٹیٹ میٹروپولیٹن شہروں میں واقع ہونا ضروری ہوگی۔ متعلقہ قوانین اور ضوابط کے تحت جہاں این او سی، منظوری یا اجازت درکار ہو، وہاں مجاز اتھارٹی سے مطلوبہ اجازت حاصل کرنا بھی لازمی ہوگا۔
مجوزہ ترامیم کا مقصد REIT انویسٹمنٹ پورٹ فولیوز میں شامل کیے جانے والے اثاثوں کی نوعیت اور محل وقوع کے حوالے سے مزید وضاحت فراہم کرنے کے ساتھ ساتھ رئیل اسٹیٹ پر مبنی سرمایہ کاری کے ڈھانچے کی ریگولیٹری نگرانی کو مزید مؤثر بنانا ہے۔
مجوزہ فریم ورک میں ہائبرڈ REIT سکیمز کے لیے بھی گنجائش پیدا کی گئی ہے، جن میں انویسٹمنٹ بیسڈ اور رینٹل دونوں حکمت عملیوں کو یکجا کیا جا سکے گا۔ ایسی اسکیمیں اپنی جائیدادوں سے کرایہ کی آمدن حاصل کرنے کے ساتھ ساتھ انہیں طویل مدت تک اپنے پاس رکھ کر ممکنہ کیپٹل گین سے بھی فائدہ اٹھا سکیں گی۔
اس نظام کے ذریعے REIT مینیجرز کو اپنے رئیل اسٹیٹ پورٹ فولیوز کے انتظام میں زیادہ لچک حاصل ہوگی، کیونکہ وہ باقاعدہ کرایہ کی آمدن کے ساتھ ساتھ جائیداد کی قدر میں مستقبل میں اضافے سے حاصل ہونے والے منافع پر بھی توجہ مرکوز کر سکیں گے۔
ایس ای سی پی نے REIT سکیموں کی لسٹنگ کی مدت کے حوالے سے بھی تبدیلیاں تجویز کی ہیں۔ مجوزہ ترامیم کے تحت اگر درخواست گزار لسٹنگ میں تاخیر کی قابلِ قبول وجوہات پیش کرے تو کمیشن رینٹل یا انویسٹمنٹ بیسڈ REIT سکیم کی لسٹنگ کے لیے ایک سال تک اضافی مہلت دے سکے گا۔
یہ شق ان REIT سپانسرز کو اضافی سہولت فراہم کر سکتی ہے جو ایسے حالات کے باعث مقررہ مدت میں لسٹنگ کا عمل مکمل نہ کر سکیں، تاہم اضافی مہلت دینے کا فیصلہ درخواست گزار کی فراہم کردہ وجوہات کا جائزہ لینے کے بعد ایس ای سی پی کرے گا۔
مجوزہ ترامیم میں سرکاری اداروں، حکومت کے تعاون سے چلنے والے اداروں یا قانونی حیثیت رکھنے والی ترقیاتی اتھارٹیز سے حاصل کی گئی رئیل اسٹیٹ کے حوالے سے بھی اہم تبدیلی تجویز کی گئی ہے۔ ایسے معاملات میں ایس ای سی پی جائیداد کی منتقلی کی قانونی شرط پوری کرنے کے لیے ناقابلِ تنسیخ اور قانونی طور پر پابند منتقلی کے معاہدے کو قابلِ قبول دستاویز قرار دے سکتا ہے، تاہم یہ منظوری ریگولیٹر کی مقرر کردہ شرائط سے مشروط ہوگی۔
اس اقدام سے سرکاری ملکیت یا ترقیاتی اتھارٹیز کے زیرانتظام جائیدادوں کو REIT سٹرکچر میں شامل کرنے کے عمل کو نسبتاً آسان بنانے میں مدد مل سکتی ہے، کیونکہ جائیداد کی منتقلی کے قانونی جواز کو ثابت کرنے کے لیے متبادل طریقہ کار دستیاب ہوگا۔
ایس ای سی پی کے مطابق مجوزہ ترامیم پاکستان میں REIT کے ریگولیٹری فریم ورک کو مزید مؤثر بنانے اور رئیل اسٹیٹ کے شعبے میں منظم سرمایہ کاری کو فروغ دینے کی کوششوں کا حصہ ہیں، جبکہ سرمایہ کاروں کے تحفظ اور اہل جائیدادوں کے لیے قانونی و ریگولیٹری تقاضوں کی تکمیل کو بھی یقینی بنایا جائے گا۔
چونکہ یہ ترامیم فی الحال مسودے کی شکل میں جاری کی گئی ہیں، اس لیے ان کی حتمی منظوری اور نفاذ ریگولیٹری عمل مکمل ہونے سے مشروط ہے۔
سکیورٹیز اینڈ ایکسچینج کمیشن آف پاکستان (SECP) نے رئیل اسٹیٹ انویسٹمنٹ ٹرسٹ (REIT) سکیموں کے ریگولیٹری فریم ورک میں ترامیم تجویز کر دی ہیں، جن کے تحت انویسٹمنٹ بیسڈ REIT سکیموں میں زرعی زمین کو شامل نہیں کیا جا سکے گا۔
ایس ای سی پی کی جانب سے یہ مجوزہ ترامیم S.R.O. 1440(I)/2026 کے ذریعے جمعہ کو جاری کی گئیں، جو رئیل اسٹیٹ انویسٹمنٹ ٹرسٹ ریگولیشنز 2022 میں مجوزہ ترامیم کا حصہ ہیں۔
مجوزہ فریم ورک کے تحت انویسٹمنٹ بیسڈ REIT سکیم کا بنیادی مقصد ایسی رئیل اسٹیٹ حاصل کرنا ہوگا جس سے مستقبل میں کیپٹل گین حاصل کیا جا سکے۔ تاہم، زرعی زمین کو اس نوعیت کی REIT سکیموں کے لیے اہل اثاثہ تصور نہیں کیا جائے گا، جس سے انویسٹمنٹ بیسڈ REIT پورٹ فولیو میں شامل کیے جانے والے اثاثوں کا دائرہ محدود ہو جائے گا۔
ایس ای سی پی کے مطابق انویسٹمنٹ بیسڈ REIT سکیموں کے لیے اہل رئیل اسٹیٹ میٹروپولیٹن شہروں میں واقع ہونا ضروری ہوگی۔ متعلقہ قوانین اور ضوابط کے تحت جہاں این او سی، منظوری یا اجازت درکار ہو، وہاں مجاز اتھارٹی سے مطلوبہ اجازت حاصل کرنا بھی لازمی ہوگا۔
مجوزہ ترامیم کا مقصد REIT انویسٹمنٹ پورٹ فولیوز میں شامل کیے جانے والے اثاثوں کی نوعیت اور محل وقوع کے حوالے سے مزید وضاحت فراہم کرنے کے ساتھ ساتھ رئیل اسٹیٹ پر مبنی سرمایہ کاری کے ڈھانچے کی ریگولیٹری نگرانی کو مزید مؤثر بنانا ہے۔
مجوزہ فریم ورک میں ہائبرڈ REIT سکیمز کے لیے بھی گنجائش پیدا کی گئی ہے، جن میں انویسٹمنٹ بیسڈ اور رینٹل دونوں حکمت عملیوں کو یکجا کیا جا سکے گا۔ ایسی اسکیمیں اپنی جائیدادوں سے کرایہ کی آمدن حاصل کرنے کے ساتھ ساتھ انہیں طویل مدت تک اپنے پاس رکھ کر ممکنہ کیپٹل گین سے بھی فائدہ اٹھا سکیں گی۔
اس نظام کے ذریعے REIT مینیجرز کو اپنے رئیل اسٹیٹ پورٹ فولیوز کے انتظام میں زیادہ لچک حاصل ہوگی، کیونکہ وہ باقاعدہ کرایہ کی آمدن کے ساتھ ساتھ جائیداد کی قدر میں مستقبل میں اضافے سے حاصل ہونے والے منافع پر بھی توجہ مرکوز کر سکیں گے۔
ایس ای سی پی نے REIT سکیموں کی لسٹنگ کی مدت کے حوالے سے بھی تبدیلیاں تجویز کی ہیں۔ مجوزہ ترامیم کے تحت اگر درخواست گزار لسٹنگ میں تاخیر کی قابلِ قبول وجوہات پیش کرے تو کمیشن رینٹل یا انویسٹمنٹ بیسڈ REIT سکیم کی لسٹنگ کے لیے ایک سال تک اضافی مہلت دے سکے گا۔
یہ شق ان REIT سپانسرز کو اضافی سہولت فراہم کر سکتی ہے جو ایسے حالات کے باعث مقررہ مدت میں لسٹنگ کا عمل مکمل نہ کر سکیں، تاہم اضافی مہلت دینے کا فیصلہ درخواست گزار کی فراہم کردہ وجوہات کا جائزہ لینے کے بعد ایس ای سی پی کرے گا۔
مجوزہ ترامیم میں سرکاری اداروں، حکومت کے تعاون سے چلنے والے اداروں یا قانونی حیثیت رکھنے والی ترقیاتی اتھارٹیز سے حاصل کی گئی رئیل اسٹیٹ کے حوالے سے بھی اہم تبدیلی تجویز کی گئی ہے۔ ایسے معاملات میں ایس ای سی پی جائیداد کی منتقلی کی قانونی شرط پوری کرنے کے لیے ناقابلِ تنسیخ اور قانونی طور پر پابند منتقلی کے معاہدے کو قابلِ قبول دستاویز قرار دے سکتا ہے، تاہم یہ منظوری ریگولیٹر کی مقرر کردہ شرائط سے مشروط ہوگی۔
اس اقدام سے سرکاری ملکیت یا ترقیاتی اتھارٹیز کے زیرانتظام جائیدادوں کو REIT سٹرکچر میں شامل کرنے کے عمل کو نسبتاً آسان بنانے میں مدد مل سکتی ہے، کیونکہ جائیداد کی منتقلی کے قانونی جواز کو ثابت کرنے کے لیے متبادل طریقہ کار دستیاب ہوگا۔
ایس ای سی پی کے مطابق مجوزہ ترامیم پاکستان میں REIT کے ریگولیٹری فریم ورک کو مزید مؤثر بنانے اور رئیل اسٹیٹ کے شعبے میں منظم سرمایہ کاری کو فروغ دینے کی کوششوں کا حصہ ہیں، جبکہ سرمایہ کاروں کے تحفظ اور اہل جائیدادوں کے لیے قانونی و ریگولیٹری تقاضوں کی تکمیل کو بھی یقینی بنایا جائے گا۔
چونکہ یہ ترامیم فی الحال مسودے کی شکل میں جاری کی گئی ہیں، اس لیے ان کی حتمی منظوری اور نفاذ ریگولیٹری عمل مکمل ہونے سے مشروط ہے۔